For buyers researching second home tax benefits in Tennessee, the most important question is not simply whether a deduction exists. It is how the home will be used, how the purchase is financed, and whether the owner itemizes deductions. The Preserve at Dale Hollow pairs architect-designed elevated homes with private wooded lots across 520 acres, about nine minutes from Dale Hollow Lake, making it a useful setting to consider the lifestyle and tax-planning sides of second-home ownership together.
Explore second-home options at The Preserve at Dale Hollow
This guide explains the main federal rules, Tennessee-specific context, and recordkeeping questions to discuss with a qualified tax professional. It is educational information, not individualized tax, legal, or financial advice. Tax rules can change, and your result depends on facts such as filing status, loan terms, personal use, rental days, and other deductions.
What are the main tax benefits of owning a second home?
A second home may create tax benefits through qualified mortgage-interest and property-tax deductions when the owner itemizes. If the property is rented, the tax treatment changes: rental income must be reported in many cases, and expenses generally must be divided between personal and rental use. The deduction is not automatic and is not the same as a tax credit.
- Mortgage interest: Interest on debt secured by a qualified second home may be deductible within federal limits when the loan is used to buy, build, or substantially improve the residence.
- Property taxes: Real property taxes may be included with other state and local taxes on an itemized federal return, subject to the applicable SALT rules and limits.
- Rental expenses: When the home is rented beyond the limited personal-use exception, eligible expenses may be deductible against rental income, subject to allocation and passive-activity rules.
- Basis records: Certain capital improvements can affect the property’s tax basis, which may matter when the home is sold.
These benefits reduce taxable income when allowed. They do not reimburse every dollar spent on the property, and they may not produce a benefit in a year when the standard deduction is larger than the owner’s itemized deductions.
Can you deduct mortgage interest on a second home?
Yes, mortgage interest on a second home can qualify under the same general framework used for a primary residence, but the owner must meet the IRS requirements. The debt must be secured by a qualified home, the loan proceeds must be used for an eligible purpose, and the taxpayer generally must itemize on Schedule A to claim the personal-use deduction.
The IRS identifies a second home as a qualified home for mortgage-interest purposes when it has basic living accommodations, including sleeping, cooking, and toilet facilities. A buyer should also confirm whether the loan is secured by the property and whether the funds were used to acquire, construct, or substantially improve that home. Interest on money borrowed for unrelated personal expenses does not receive the same treatment.
For many newer mortgages, federal law limits the amount of acquisition debt on which interest can be deducted across a taxpayer’s qualified homes. The applicable limit depends on the loan date, filing status, and debt history. Use the current IRS Publication 936 and ask a tax professional to review the numbers rather than relying on a headline limit.
Points, refinancing, and construction financing can have separate timing rules. If you are buying a home that is still being built, the interest treatment may depend on when construction begins and whether the finished property becomes a qualified home. Keep the closing statement, Form 1098, loan documents, and records showing how borrowed funds were used.
Talk with The Preserve about a second-home tour
Are property taxes on a second home deductible?
Property taxes on a second home may be deductible on a federal return when the owner itemizes, but they are generally part of the broader state and local tax calculation. The deduction is subject to the federal SALT rules in effect for the tax year. A property-tax bill is not a dollar-for-dollar tax credit, and itemizing is required for the personal deduction.
The IRS distinguishes a tax imposed for the general public welfare from charges for a specific service or local improvement. That means an owner should not assume that every line on a county, city, assessment, or community statement is treated identically. Review the statement and retain documentation for property taxes, assessments, insurance, utilities, association charges, and maintenance separately.
Tennessee’s tax environment is part of the broader ownership conversation, but it does not eliminate federal filing requirements. Tennessee repealed its Hall income tax beginning January 1, 2021, and the state does not impose a broad individual wage income tax. That context may matter to buyers comparing states, yet it should not be presented as a guaranteed deduction or as a promise that a second home will lower an individual tax bill.
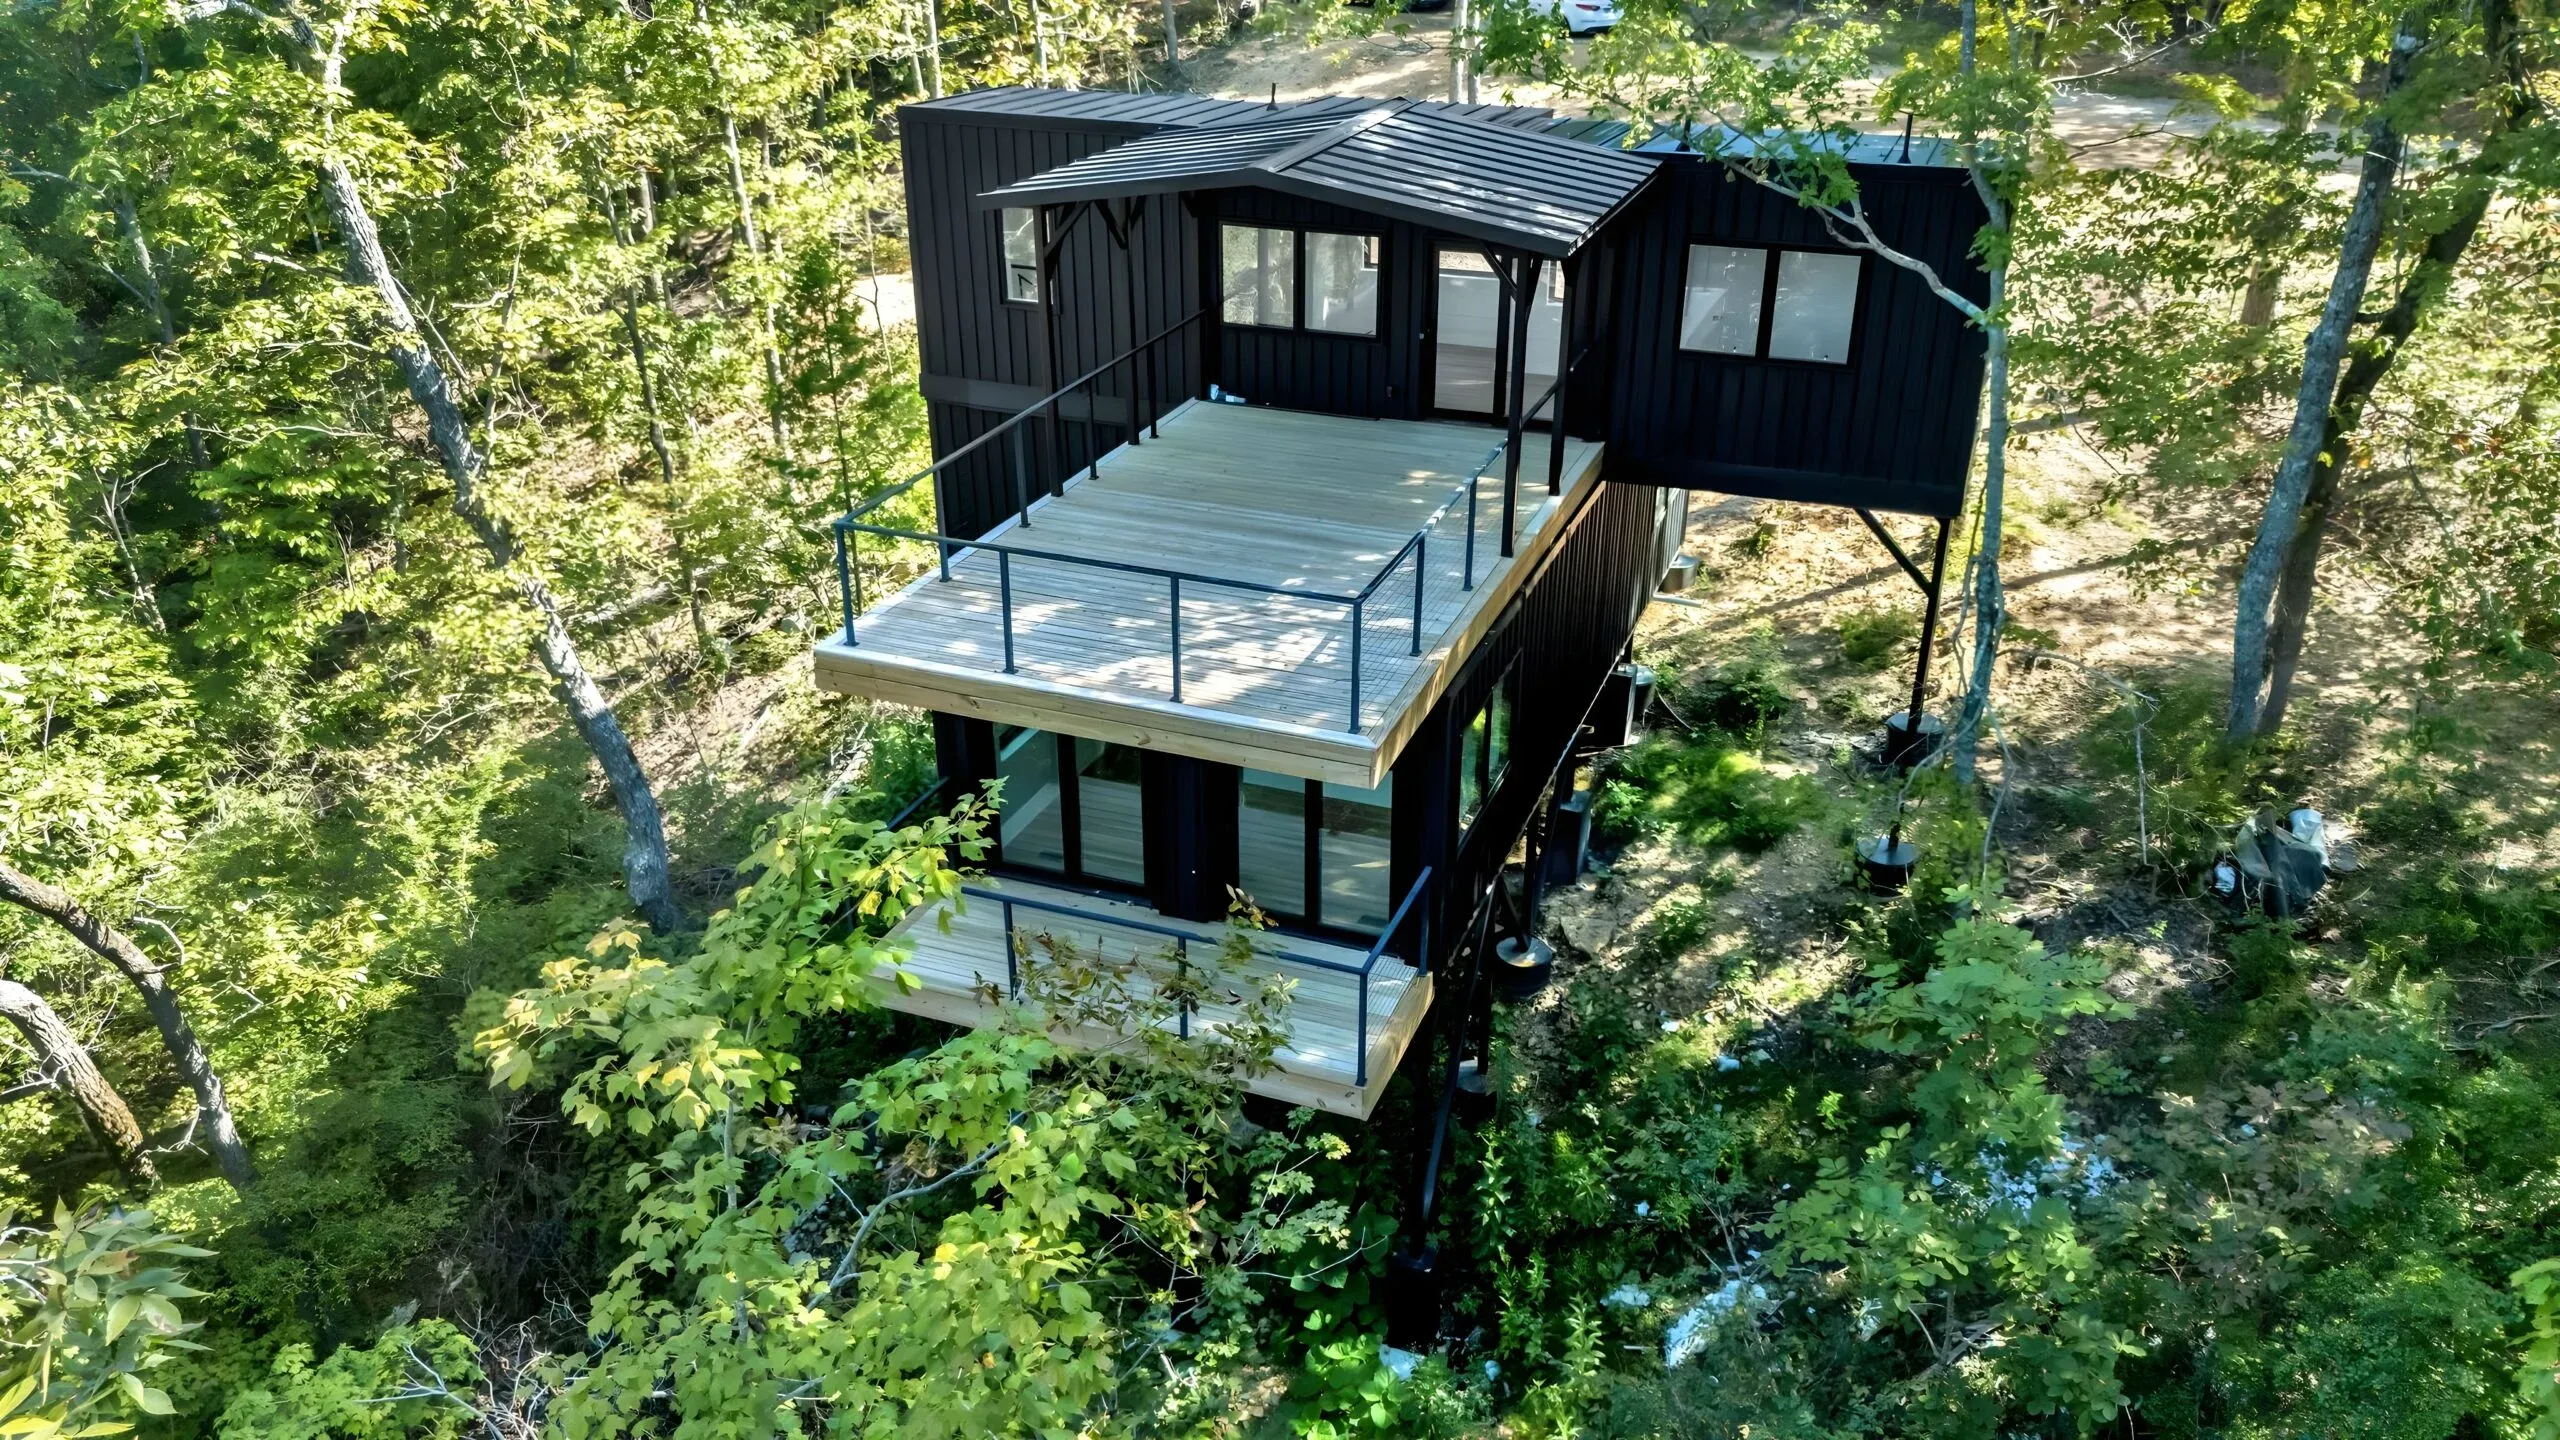
The setting can still matter financially in a practical sense. The Preserve at Dale Hollow gives buyers a defined community context, modern elevated architecture, and valley views near Dale Hollow Lake. Those features help a buyer evaluate the property as a long-term personal and possible rental asset, while the actual tax result remains a separate professional review.
How does renting a second home change the tax picture?
Rental use changes both reporting and deductions. If you rent a second home for 14 days or fewer during the year, the federal tax treatment is generally different from a property rented for more than 14 days. Once rental activity exceeds that limited exception, the owner usually reports rental income and allocates shared costs between personal and rental use.
| How the home is used | General tax question | Records to keep |
|---|---|---|
| Personal use only | Can qualified mortgage interest and property taxes be claimed if you itemize? | Loan statements, Form 1098, tax bill, closing documents |
| Rented 14 days or fewer | Does the limited-rental exception apply for the year? | Rental calendar, booking records, personal-use calendar |
| Rented more than 14 days | How should income and shared expenses be reported and allocated? | Gross receipts, platform statements, invoices, days of use |
| Primarily rental use | Do passive-activity, depreciation, or business-use rules apply? | Expense ledger, improvement records, depreciation schedule |
The IRS Publication 527 explains the residential rental rules, including personal-use days, expense allocation, and depreciation. A buyer should not decide how to classify a property based only on the name used in a listing. The actual calendar, rental agreement, personal use, and services provided all matter.
For a Tennessee short-term rental, owner income-tax reporting is only one layer. The Tennessee Department of Revenue also addresses sales and use tax, local occupancy tax, business tax, and marketplace or property-manager responsibilities. Its Short-Term Rental Units manual notes that lodging taxes can apply to taxable stays and that local rates and collection responsibilities vary. Those guest-facing taxes are not the same as a personal mortgage-interest deduction.
Which expenses should a second-home buyer track?
Strong records make a tax conversation more useful and reduce the risk of mixing personal, rental, and capital expenses. Before closing, create a simple system that separates acquisition documents, recurring ownership costs, rental activity, and improvements. The goal is not to claim every expense. It is to give your tax professional enough detail to apply the right rule.
Acquisition and financing records
- Closing disclosure and settlement statements
- Loan agreement, interest statements, and Form 1098
- Records showing how loan proceeds were used
- Invoices for qualifying improvements and construction work
Annual ownership records
- County or city property-tax bills and payment confirmations
- Insurance, utilities, maintenance, and association statements
- Travel or management records when a professional advises that they are relevant
- Receipts that distinguish repairs from capital improvements
Rental records
- Booking calendars showing guest days and personal-use days
- Platform statements and gross rental receipts
- Cleaning, management, supplies, and other operating invoices
- Separate records for lodging taxes collected or remitted by a marketplace
Keep a calendar that shows every day the home was occupied, whether by the owner, family, guests, or a manager. That one habit helps explain why a cost was allocated a certain way and gives a tax professional a clearer starting point.
How should Tennessee buyers evaluate tax benefits before buying?
Tax benefits should support a purchase decision, not drive it by themselves. Start with the intended use, then model ownership costs without assuming a deduction. A home that works for your family, travel pattern, and long-term goals is more resilient than a purchase that depends on an unverified tax estimate.
- Define the primary use: Decide whether the home is mainly personal, mixed-use, or rental-focused.
- Ask how the lender treats the property: Confirm second-home or investment-property requirements before assuming a loan structure.
- Estimate the full carrying cost: Include principal, interest, insurance, property taxes, utilities, maintenance, management, and travel.
- Separate federal and Tennessee questions: Mortgage interest, itemizing, rental income, and Tennessee lodging taxes can involve different rules.
- Get a written professional review: Ask a CPA or enrolled tax professional to review a projected use calendar and expected documents.
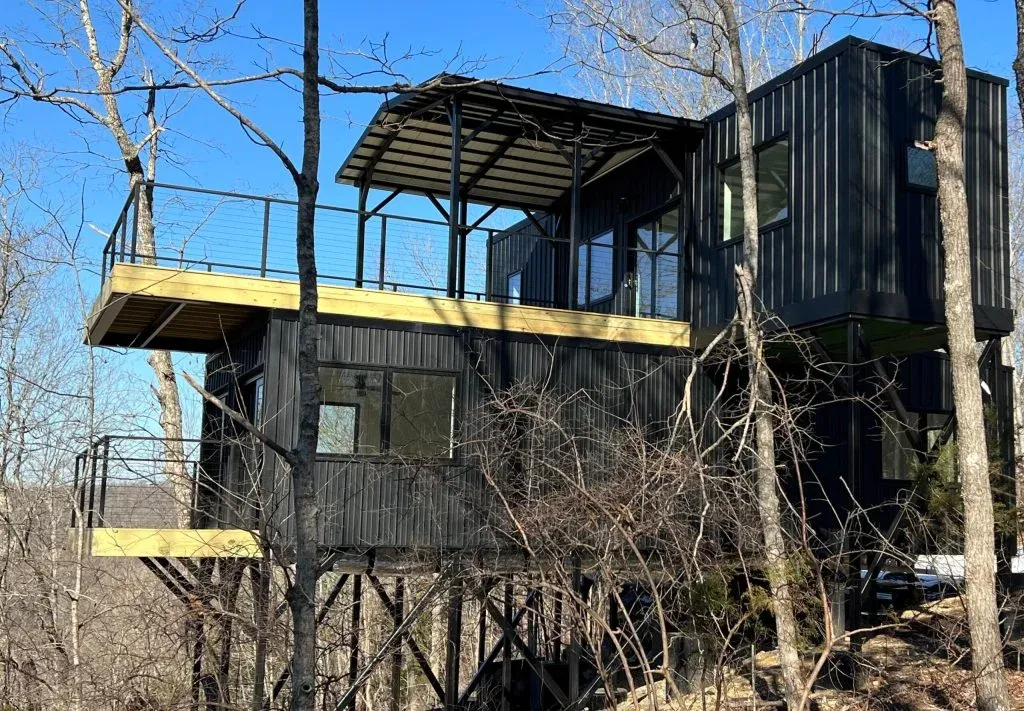
The Preserve at Dale Hollow is positioned for buyers who want a modern retreat near the lake and the flexibility to explore personal use alongside rental use. Its 520-acre setting, architect-designed homes, floor-to-ceiling windows, and rooftop decks are ownership considerations. They are not substitutes for a tax plan or a guarantee of income.
For broader purchase context, compare this tax-focused guide with the out-of-state second-home buying guide and the discussion of Dale Hollow Lake property values. Those resources address ownership and property considerations; this article is intentionally focused on tax questions.
What should you ask a tax professional about a second home?
Bring a short, fact-based summary to your tax professional: purchase date, loan amount and purpose, expected personal-use days, expected rental days, state of residence, filing status, and a list of projected expenses. Ask which deductions may apply, how shared costs should be allocated, and which records should be retained.
- Will itemizing create a federal benefit in my situation?
- What mortgage-interest limits apply to my existing and new home debt?
- How should personal and rental use be divided?
- What Tennessee lodging or business-tax obligations could apply if the home is rented?
- How should improvements and selling costs be tracked for basis purposes?
Request information and plan your next step with The Preserve
Second home tax benefits FAQ
The short answer is that a second home may offer qualified deductions, but the result depends on use, financing, itemization, rental activity, and current law. The questions below are a starting point for a conversation with a qualified tax professional before you buy or begin renting.
Is mortgage interest on a second home tax deductible?
It may be deductible when the debt is secured by a qualified second home, used for an eligible acquisition or improvement purpose, and claimed by a taxpayer who itemizes, subject to applicable federal limits.
Can I deduct property taxes on a second home?
Property taxes may be included in an itemized federal deduction subject to the current SALT rules. Charges for services or local improvements may be treated differently, so keep the bill’s line items and ask for professional guidance.
What is the 14-day rule for a vacation home?
In general, renting the home for 14 days or fewer can trigger a limited-rental exception. Renting beyond that threshold usually means reporting rental income and allocating expenses between personal and rental use.
Does Tennessee have a state income tax on second-home income?
Tennessee repealed its Hall income tax beginning January 1, 2021, but federal reporting and other Tennessee taxes can still apply. Short-term-rental sales, occupancy, business, and related obligations should be reviewed separately.
Is a second home automatically a good tax investment?
No. A deduction is not the same as a profit, and tax treatment cannot correct an unsuitable property, weak operating plan, or unplanned carrying costs. Evaluate the home on its lifestyle and financial fundamentals first.
For official guidance, start with the IRS real-estate deduction FAQ, then ask a qualified tax professional to apply the current rules to your circumstances.